Snap Finance
Snap FinanceShoppingVerified
- 630.00 Reviews
- 4.8
- Downloads
- 100,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
I think the most useful way to judge Snap Finance is to focus on the choice it puts in front of a shopper: whether paying over time is a better fit than waiting, paying in full, or using another way to cover a purchase. Snap Finance is a free shopping app from Snap Finance, built around access to financing without requiring credit. That can make a necessary purchase feel more reachable, but it does not make the purchase cheaper or remove the need to plan repayments. I’d treat it as a way to consider a payment option, not as extra income.
What “no credit needed” changes—and what it does not
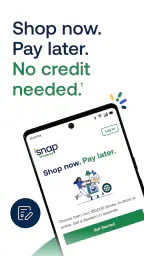
For someone who has limited credit history or would rather not make a strong credit score the first hurdle, the app’s central promise is appealing. It offers another route to explore when a purchase cannot easily wait. That distinction matters: not needing credit is not the same as not needing to qualify, and it should never be read as automatic approval. I would approach the application with the same care I’d use for any financial commitment and read the terms shown before deciding.
The app’s shopping focus also sets it apart from a general budgeting tool or a standard bank app. Its purpose is not to help me track every household expense or compare every payment method on the market; it is to connect shopping with a financing option. That narrower role can be useful when I already know what I need to buy. It is less compelling if I’m simply looking for a broad financial dashboard or a way to manage day-to-day spending.
How I’d use it before committing
I’d start by treating the app as a decision checkpoint rather than rushing straight from browsing to a payment plan. Before applying, I’d work out the amount I can comfortably put toward the purchase and what room remains in my monthly budget after rent, utilities, food, transport, and existing obligations. Then I’d compare that figure with the payment schedule and full cost presented during the process. If the schedule only works in a perfect month, I’d wait or choose a cheaper option.
That little bit of preparation is especially useful because the convenience of spreading a cost can make a purchase feel smaller than it really is. I’d keep a note of the payment dates somewhere I already check, and make sure the money will be available before each one. Even if an app helps me follow payments, my own calendar and budget are still the safer backstop. I would also avoid taking on a new plan just because the application feels quick; speed is convenient, but it is not a substitute for deciding whether the commitment fits.
It helps to ask one practical question before starting: would I still buy this item if I had to pay for it in full today? If the answer is no because it is optional or beyond my means, financing may only postpone the problem. If the item is genuinely needed and delaying it would cause a greater cost or disruption, a payment option may be worth examining—provided the terms and repayment timing make sense. That is the judgment call I’d want the app to support, rather than a reason to spend more.
A realistic use case: replacing something essential
Imagine a household appliance stops working just before a busy week. Replacing it may be necessary, but the timing could be awkward if the available cash is already assigned to other bills. In that situation, I’d use Snap Finance to explore whether a suitable purchase and its payment schedule fit the budget, then compare that with waiting, choosing a lower-cost replacement, or using savings. The app is most useful here as one option in a short list—not as an automatic answer.
Other Stories to Read
The same reasoning applies to a repair or another necessary expense: first separate the urgent need from any optional upgrades, then consider only the amount required to solve the problem. A shopper might be tempted to bundle a better model or extra items into the purchase because the upfront amount appears more manageable. I’d resist that unless I could afford the larger commitment without relying on optimistic assumptions. Keeping the financed purchase focused is a simple way to make the decision easier to evaluate later.
By contrast, I would be cautious about using a financing app for small treats, impulse buys, or several unrelated purchases. Each one may seem manageable on its own, but overlapping obligations can make a future month tighter than expected. If I already have a repayment plan or uncertain income, I’d pause and calculate the combined effect before adding another commitment. In those circumstances, saving up or postponing the purchase is often the more comfortable choice.
How it compares with paying in full or using a card
Paying in full is simpler when the money is available: there is no new repayment schedule to remember, and the purchase does not compete with future bills. A credit card may offer a familiar way to handle timing, but it brings its own terms and can become expensive if a balance carries over. Snap Finance is worth considering when its particular financing route suits the purchase and the terms work for the shopper. I would not assume it is automatically cheaper or better than either alternative; I’d compare the total commitment, timing, and consequences of missing a payment before choosing.
There is also a useful difference between financing a planned necessity and borrowing to make a discretionary purchase feel affordable. The former can solve a timing problem if handled carefully. The latter can disguise a budget problem. I’d compare the app with a simple savings plan as well: waiting may be frustrating, but it avoids adding a repayment to future months. If the item can safely wait, that alternative deserves serious consideration.
For shoppers who want a full view of their finances, a bank’s own app or a dedicated budgeting tool may be more useful alongside—or instead of—Snap Finance. Those tools can help with broader spending decisions, while this app is centered on shopping finance. I would not expect one focused app to replace a household budget. The practical approach is to use whichever tool gives me the clearest view of the commitment, then keep the full household picture in mind.
Where the experience may need patience
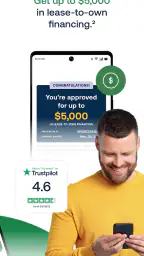
The app has an average rating of 4.8 from around 6,300 ratings, which suggests many people have found it useful, but a rating cannot tell me whether a particular plan fits my finances. Snap Finance has more than 100,000 installs, and its current version is 2.2.10543. It is rated for everyone and is free to download, but the financing decision itself still deserves adult attention and careful reading. The app was released on March 29, 2023, and works on Android 7.0 or later.
I’d also keep expectations measured around support and first-time setup. In my experience, customer service could be more responsive during busy periods, and someone new to financing may want clearer guidance while completing an application. If I had a question that affected whether I should accept an offer, I would wait for a clear answer instead of guessing. A quick process is only helpful when I understand what I’m agreeing to.
Before relying on the app for a time-sensitive purchase, I’d make sure I have enough time to review the offer and consider a backup plan. That could mean checking whether the purchase can wait, identifying a less expensive alternative, or asking the seller about other ways to pay. This is not because the app is inherently difficult; it is simply sensible not to leave an essential purchase dependent on a decision I have not yet received or understood.
Getting Started with Snap Finance
First things first, downloading and setting up Snap Finance is a breeze. Available on both Android and iOS, you simply head over to your app store, hit download, and you’re good to go. The setup process is straightforward and user-friendly. Within minutes, I was up and running, ready to explore all the app had to offer.
Once inside, the app greets you with a clean and intuitive interface. It’s designed to be user-centric, making navigation as simple as pie. I didn’t have to hunt for features—the app practically hands them to you on a silver platter.
Features That Stand Out
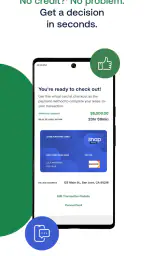
One of the standout features of Snap Finance is its accessibility. Unlike traditional financing options, this app doesn't require a perfect credit score. The application process is quick, and you usually get a decision within minutes. Talk about efficiency!
I was impressed by the variety of payment options available. You can choose from flexible payment plans that suit your financial situation. This level of customization is a game-changer, especially for those of us who like to keep our financial ducks in a row.
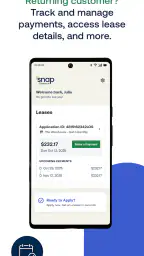
The app also offers a handy tool for managing your payments. You can track your payment history, view upcoming payments, and even set reminders. It’s like having a personal assistant keeping tabs on your finances.
My Experience with Snap Finance
Using Snap Finance felt like a breath of fresh air compared to other financing apps. I remember needing to cover an unexpected car repair. Instead of scrambling for funds, I turned to Snap Finance, and within minutes, I had the funds ready to go. No hoops to jump through, just simple and straightforward service.
The transparency of the app is another point worth mentioning. They lay out all the terms and conditions in a way that’s easy to digest. There’s no fine print trying to trip you up later on, which is something I really appreciated.
What Could Be Improved?
While Snap Finance has a lot going for it, there’s always room for improvement. One thing I noticed was that the customer service, although helpful, could be a bit more responsive. During peak times, it took a little longer than expected to get answers to my questions.
Additionally, while the app is pretty straightforward, some users might find the initial application process a bit daunting. A little more guidance or an in-app tutorial could go a long way in making new users feel more comfortable.
Final Thoughts
All in all, Snap Finance is a solid option for anyone in need of quick and easy access to funds. It’s user-friendly, flexible, and incredibly convenient. Whether you’re dealing with an emergency or just need a little extra to cover expenses, this app has got your back.
Would I recommend it? Absolutely. For anyone wanting a simple, no-fuss financial solution, Snap Finance is worth checking out. Just keep an eye on those customer service wait times, and you’ll be golden.
So, the next time you’re caught in a financial bind, remember you’ve got an ally in Snap Finance. It’s like having a financial superhero in your phone, ready to swoop in and save the day.
Highlights
- Flexible payment options available.
- Quick and easy approval process.
- No credit needed to apply.
- User-friendly interface design.
- Wide range of retailers supported.
Limitations
- High interest rates on financing.
- Limited availability in some areas.
- Mobile app lacks some features.
- Customer service response times vary.
- Not all purchases qualify for financing.
Frequently Asked Questions
01What is Snap Finance, and how does it work?
Snap Finance is a financial service app that provides users with lease-to-own financing options for purchasing products. It is designed for those who may have limited or no credit history. Users can apply through the app, get approval in seconds, and use their approved amount to shop at participating retailers. Payments are made over time, making it a convenient option for many.
02Do I need a good credit score to use Snap Finance?
No, Snap Finance does not require a good credit score. It offers an alternative to traditional financing by considering other factors such as income and banking history. This makes it accessible to individuals who might not qualify for conventional credit options. The application process is straightforward and does not involve a hard credit check.
03How do repayments work with Snap Finance?
Repayments for Snap Finance are typically structured over a 12-month period, but users can choose to pay off their balance sooner if they prefer. Payments are automatically deducted from the user’s bank account on scheduled dates. The app provides reminders and account management tools to help users stay on top of their payments and avoid late fees.
04What products can I purchase using Snap Finance?
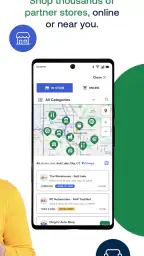
Snap Finance can be used to purchase a wide range of products, including electronics, furniture, and appliances, from participating retailers. The app provides a list of partner stores and offers users the flexibility to shop both online and in physical stores. This versatility makes it a convenient option for various shopping needs.
05Are there any fees associated with using Snap Finance?
Snap Finance does not charge any hidden fees, but users should be aware of interest rates and any potential late payment fees. The total cost of the lease-to-own agreement is made clear before users commit, allowing them to make informed decisions. Early payoff options may also help reduce costs by saving on interest.


